Industry
Part of Term loans, matched to what they buy: amortisation compared against asset life
7 points on term loans rules that matter
Term loans rules live in your own stack of documents, not in a published code. A reading procedure: definitions first, then seven points before signing.
The rules that will actually govern your term loan are not published anywhere. They are in a stack of paper you will be handed shortly before you are expected to sign it, and the stack is larger and stranger than most borrowers expect.
This is a reading procedure for that stack. It assumes nothing about your lender, because the rules that matter are the ones in your own set of documents rather than anything general.
What to take away
- You sign a set of documents, not one, and they do different jobs.
- Read the definitions before anything else. They redefine ordinary words.
- Ask for the whole set before signing day, in a version you can keep.
What is actually in the stack
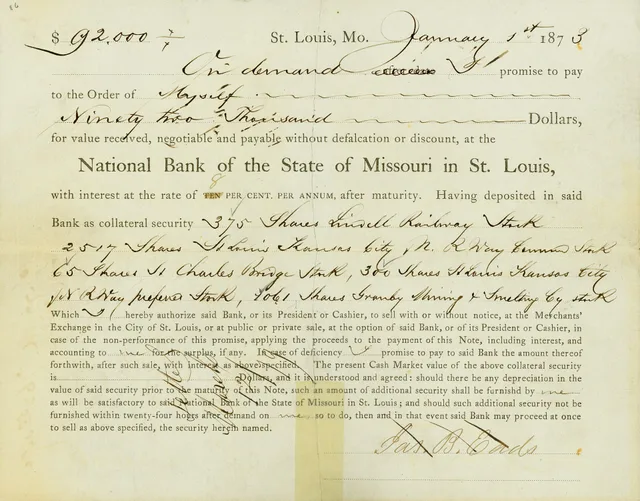
The names vary, and not every file contains every item, but the jobs are consistent. A typical small business term loan comes as a promissory note (the promise to pay: amount, rate, schedule), a loan agreement (definitions, covenants, default triggers), a security agreement (what is pledged), a guaranty (a separate personal contract), a UCC-1 financing statement (the public filing that perfects the pledge), and corporate resolutions or other authorizing documents (proof that the signer can bind the business).
What the Loan Stack Contains
- The notepromise to repay
- Loan or credit agreementconditions
- Security agreementwhat is pledged
- Public filingtells the world
- Guaranteesigned in your own name
- Disclosures, resolutions, insurance, certificates
Ask for all of it at once. A set read in fragments, on different days, is a set where the cross-references never get checked.
Read the definitions first
Defined terms are the part everyone skips and the part that changes meanings. A capitalised word in one of these agreements does not mean what the same word means in conversation.
What 'Default' Actually Means
Everyday meaning
- Missed payment
- The whole meaning
- Reporting deadline
- Not a default
- Ratio breached
- Not a default
- Asset sold
- Not a default
- Ownership change
- Not a default
- Unrelated obligation
- Not a default
In a loan agreement
- Missed payment
- One item on a list
- Reporting deadline
- Usually a default
- Ratio breached
- Usually a default
- Asset sold
- Usually a default
- Ownership change
- Usually a default
- Unrelated obligation
- Usually a default
The one that catches people is default. In ordinary use it means a missed payment.
In a loan agreement it is usually a defined list, and most items have nothing to do with payment: a reporting deadline missed, a debt service coverage or leverage ratio breached, an asset sold, an ownership change, a default on an unrelated obligation.
Read the definitions section first, mark every term you would have guessed at, then read the rest. The document becomes a different document.
The seven points
Read for one question at a time. Trying to absorb the whole thing in one pass is how provisions get missed.
The Six Passes Before Signing
- The moneyamount, schedule, every charge
- What triggers a default, plus cure periods
- What you have pledged, and who guarantees
- What you must keep doing, into a calendar
- What you cannot do without consent
- What happens in a dispute, and recourse
- The money.Amount, disbursement, schedule, cost basis, and every charge. Reconcile these against your comparison, because the offer and the documents are not always identical: the normalizing work is set out in term loans comparison.
- What triggers a default.The defined list, plus any cure period, plus whether default makes the whole balance immediately due.
- What you have pledged.Whether the security is a specific asset or everything you own, whether it reaches assets you acquire later, and whether the filing that perfects it has actually been made.
- What you must keep doing.Statements, returns, certificates, insurance, reporting dates, and the financial tests behind them — debt service coverage, leverage, minimum liquidity — with the level at which each is measured. Put every one into a calendar before the file goes in a drawer.
- What you cannot do without consent.Additional borrowing, asset sales, ownership changes, distributions. These constrain ordinary decisions for years.
- What happens in a dispute.Who pays for it, where it happens, and what recourse you keep. Have a lawyer read anything that removes your ability to be heard before a judgment is entered.
- The guarantee, which stands on its own.It is a personal contract rather than part of the business's obligations, and it usually carries waivers worth naming: a jury trial waiver, consent to venue, a waiver of defenses, and whatever recourse the lender keeps against you personally for a deficiency after it sells the collateral.
The cross-reference trap
The body of an agreement is rarely the whole agreement. A schedule, an exhibit or an incorporated document can change what the body appears to say, and a single sentence saying that another document is incorporated by reference makes that document binding on you.
Two Habits Against the Cross-Reference Trap
- Check every reference to a schedule
- Confirm the schedule is actually attached
- Note anything incorporated by reference
- Ask for a copy before signing, not after
Two habits protect against it. Check every reference to a schedule and confirm the schedule is actually attached. Note anything incorporated by reference and ask for a copy of it before signing rather than after.
What can change after signing, and what cannot
Terms already agreed do not move because a lender's policy changed afterwards. If you are told your loan has changed, ask to be shown the provision in your own documents that permits it. That request is reasonable and it is answerable.
What Can Move After Signing
Cannot move
- Agreed terms
- Fixed by your documents
- Variable cost
- Not tied to index
- Fee schedule
- Locked
- Repayment
- Term loan schedule
- Anything else
- Needs your signature
Can move
- Agreed terms
- Only if documents allow
- Variable cost
- Moves with the index
- Fee schedule
- Amendable if agreement allows
- Repayment
- On demand if facility allows
- Anything else
- Needs your signature
What can move is anything the documents themselves allow to move, and a variable cost tied to an external index changes when the index does. A fee schedule that the agreement lets the lender amend can be amended. A facility repayable on demand can be demanded.
That difference between those terms and a genuine unilateral change is exactly the difference between a term loan and a revolving facility, so read lines of credit on a different basis.
Anything else takes an amendment that you sign. Keep the amendments with the original set.
Before signing day
- Ask for the complete set, in advance, in a form you can keep and search.
- Read the definitions, then work through the seven points.
- Search your state's UCC filing office for filings against the business.
- Write down every question and get the answers in writing, not on a call.
- Reconcile the documents against the offer that persuaded you.
- Have a lawyer read the guarantee and anything affecting your legal recourse.
- Keep a signed copy of everything, including schedules and exhibits.
Signing day is not the time for the first read. The provisions that decide how a difficult year goes are described in application and repayment, and the ones people discover too late are collected in term loans.
Where to check anything specific
Your documents govern, and no article can tell you what is in them. What is public is the pledge: security interests in business assets are governed by Article 9 of the Uniform Commercial Code, and your lender perfects its claim by filing a UCC-1 financing statement with your state's filing office, usually the Secretary of State, where you can search for filings against the business name — before you sign and again afterwards.
Federal and state law sit behind the paperwork too. The Equal Credit Opportunity Act and Regulation B require a lender to give a business credit applicant notice of the action taken on the application; your state's usury limit caps the interest that can be charged; and if the loan is SBA-guaranteed, the SBA's own application and authorization forms and program requirements sit on top of the lender's documents. For neutral background on business borrowing generally, the SBA business guide and the FDIC's Money Smart for Small Business are reasonable starting points with nothing attached.
Common questions
Can the lender change my terms after closing?
Only where your own documents permit it, or by an amendment you agree to. Ask to be shown the clause relied on.
Do I really need a lawyer?
For the guarantee and for anything affecting your legal recourse, yes. For the rest, a careful read against the seven points will surface most of what matters.
Why does the guarantee come as a separate document?
Because it is a separate contract, made by you personally rather than by the business. That is also why it can survive the loan and the sale of the company.
What if a schedule is missing at signing?
Do not sign until it is produced. An incorporated document you have never seen is still binding on you.