Features
Prairie equipment financing and the harvest cycle, explained for Manitoba and Saskatchewan
Prairie farm equipment financing in Canada: how FCC, MASC Direct Loans, Canadian Agricultural Loans Act guaranteed bank loans and dealer finance such as John Deere Financial time repayment to the Manitoba and Saskatchewan harvest.
What to take away
- Prairie equipment finance is built around one factincome arrives in a short harvest window, so the repayment calendar matters as much as the rate. For the wider picture, see small business loans in Canada.
- Farm Credit Canada (FCC), MASC Direct Loans in Manitoba, a bank loan guaranteed under the Canadian Agricultural Loans Act (CALA) and dealer finance each treat the same combine or air seeder differently.
- The Canada Small Business Financing Program (CSBFP) does not lend to farming businesses. Its own FAQ sends farmers to CALA instead.
- Amounts below are Canadian dollars and Canadian programs. A US-based operation should look at USDA Farm Service Agency lending instead.
How the main routes compare
Rates change often. FCC and the dealer finance arms post no equipment rate on their public pages, and MASC lists its rates separately, so the table compares structure. Ask each lender for the current rate in writing.
| Route | Who lends | Equipment term | Payment frequency | Key limit |
|---|---|---|---|---|
| FCC dealer financing | Farm Credit Canada | Up to 10 years | Not stated on FCC's page | Zero down under $100,000; 10 percent down under $500,000; no prepayment penalty |
| MASC Direct Loan (Manitoba) | Manitoba Agricultural Services Corporation | New up to 10 years; used up to 7 | Monthly, quarterly or semi-annual | Up to $6.25 million at up to 80 percent financing |
| CALA guaranteed loan | Participating bank or credit union | Up to 10 years for non-land loans (per CIBC) | Lender sets | Up to $350,000 for equipment; Ottawa guarantees 95 percent of a net loss |
| Dealer financing | John Deere Financial, CNH Industrial Capital Canada | Set by the offer | Seasonal structures offered | Rates described only as competitive; no posted figure |
| CSBFP loan | Participating lender | Not available to farming | Not applicable | Excluded for farm businesses |
For scale only: at an assumed 7.5 percent over 60 months, $200,000 costs about $240,500 in total. Those rates are our assumption, not any lender's quote.
Why the harvest cycle sets the repayment calendar in Manitoba and Saskatchewan
A Manitoba grain farm sells most of its crop in a few weeks. A Saskatchewan cattle or pulse operation may sell steadily, but its heaviest costs land in spring. Lenders who work in the region know this. They do not expect twelve equal monthly payments from a business whose revenue is lumpy.
Prairie cash flow calendar
- Springinputs bought, heaviest costs
- Growing seasonmoney out, no revenue
- Harvestcrop sold in a few weeks
- Novembercheque clears, payment lands
The repayment calendar is the first thing to negotiate, before rate. A payment that lands in March, when inputs are bought, is a different product from one that lands in November, after the cheque clears.
The BDC loan versus bank loan comparison for working capital frames it: money in, money out, the gap between them, and the date the gap closes. A working capital line covers that gap. A term loan on a machine does not, and a schedule that treats the two as interchangeable will fail in April.
Weather moves both yield and the date money arrives. A wet fall in Manitoba or a dry June in Saskatchewan makes any fixed due date risky. Lenders who last across the Prairies build a little room into the calendar.
Farm Credit Canada and the CALA guarantee compared
Farm Credit Canada is a federal Crown corporation that lends only to agriculture and agri-food. Its dealer financing program offers equipment terms up to 10 years, variable or fixed rates, no prepayment penalties and no FCC fees, with zero down on loans under $100,000 and 10 percent down under $500,000. FCC says terms of 7 to 10 years are typical for new equipment and 5 to 7 for used.
FCC vs CSBFP backed loans
FCC
- Who you deal with
- One ag lender
- Risk bearer
- FCC
- Payments
- Around production cycle
- Best for
- Established farms
- Security
- Ag assets
CSBFP backed
- Who you deal with
- Bank or credit union
- Risk bearer
- Program shares risk
- Payments
- Lender's schedule
- Best for
- Thin balance sheets
- Security
- Registered eligible assets
FCC can also time payments to the farm calendar on some products. Its input financing allows up to 18 months to pay, and purchases made after September 1 are not due until March 15. Ask whether an equipment loan can be structured the same way, because FCC's equipment page does not list payment frequencies.
The federal guarantee for farm lending is the Canadian Agricultural Loans Act. The government guarantees 95 percent of a net loss on an eligible loan made by a participating lender. Equipment and other non-land loans are capped at $350,000, and a farm can hold up to $500,000 in CALA loans at one time. CIBC lists a variable rate cap of prime plus 1 percent.
The CSBFP is the program most small business articles mention, but its FAQ states that farming businesses are not eligible. Do not plan a combine around it. Farm-related service businesses can qualify, so a custom operator or a grain-hauling company is a different case from a farm.
With FCC you deal with one agricultural lender from application to renewal. With a CALA loan you deal with a bank or credit union, and the guarantee sits behind the loan. The bank's credit policy still decides, but the guarantee can move a marginal file forward.
Both routes reward a clean set of records. A dealer quote, a serial number, a field plan and three years of statements do more for approval than any argument about loyalty. The equipment financing checklist lists the file in order.
If you are weighing the two, the useful question is ownership versus payment: do you need the lowest payment now, or the clearest path to owning the machine outright?
Check the number the week you sign, not the month you apply. Ask each lender for the same machine, the same down payment and the same payment frequency, then compare total cost, not the headline rate.
A 10-year amortisation on the same $200,000 cuts the payment to roughly $2,320 a month at an assumed 7 percent and adds about $78,600 of interest across the full term. The shorter term costs more each month and less in total. Match the term to how long you expect to keep the machine, as term loans, matched to what they buy explains.
Dealer financing and how it prices the same machine differently
Dealer financing is the fastest route to a machine, and often the most expensive if you stop reading at the monthly figure. A dealer quotes a payment, not a rate, and the payment hides the term, the residual and the buyout.
Dealer quote vs term loan
Dealer financing
- What is quoted
- Monthly payment
- Hidden parts
- Term, residual, buyout
- Trade-in
- Bundled into deal
- Promo rates
- Short term, big balloon
- Service tie
- Locked to dealer
Bank or FCC term loan
- What is quoted
- Rate and term
- Hidden parts
- Amortisation period
- Trade-in
- Separate negotiation
- Promo rates
- Standard pricing
- Service tie
- Independent
Manufacturer finance arms are the main dealer route. John Deere Financial's Canadian site offers farm equipment loans and leases "customized to your production cycle and harvest," plus a Multi-Use Account for parts, service, seed, feed and fertilizer. CNH Industrial Capital Canada Ltd. approves Case IH and New Holland contracts and has described payment schedules fitted to crop sales.
Neither posts a rate. Promotional rates usually come with a short term and a large balloon. That is fine if you plan to trade at the end of it and dangerous if you plan to keep the machine. Confirm the offer's end date with the dealer.
Dealers also price the trade differently. A dealer who wants your old tractor will sharpen the financing to win the whole deal. A dealer who does not may offer a low rate and a weak trade. The two numbers are one negotiation, so treat them as one.
Dealer financing also ties you to the dealer for service. Across the Prairies the nearest dealership can be an hour or more away, so that relationship has real value during harvest. A breakdown in September is a financing problem as much as a mechanical one.
Tax treatment separates a lease from a loan. If the contract is a true lease, the payments are a deductible operating expense and you never own the machine. If it is a loan, you claim capital cost allowance on the machine and deduct the interest.
The Canada Revenue Agency treats a lease that hands you ownership at the end, or lets you buy the machine for a nominal sum, as a purchase, so the deduction changes shape. Run both versions with an accountant before you sign.
BDC is another lender to ask about. Its general Equipment Loan covers up to 125 percent of the purchase price and can postpone principal payments for up to 24 months, with repayment over up to 12 years. BDC's page does not say whether a farm qualifies, so ask before you count on it.
Building a repayment schedule around commodity prices
Loans by industry come down to cash-flow timing. Canola, wheat, cattle and hogs do not move together, so a mixed farm has a natural hedge that a single-crop operation lacks. Lenders price that difference, whether they say so or not.
Start with the dates, not the amount. Work out when cash actually arrives: delivery dates, contract terms, and the lag before payment. Then work out when it leaves: seed, fuel, fertilizer and repairs. The gap between the two is what a repayment schedule has to survive.
Build the repayment schedule
- List expected receipts by month
- List every fixed payment
- Mark months outflows exceed inflows
- Choose payment frequency that works
- Get the schedule in writing
A worked example makes it concrete. Suppose a Saskatchewan operation buys a used air seeder for $180,000 with $30,000 down, leaving $150,000 to finance. An annual payment after harvest keeps March clear. A monthly payment of the same total may look smaller and still fail in April, when inputs are bought and no crop has been sold.
Flexibility has a price. Lenders who allow a skip or a deferral usually charge for it, either in rate or in a fee. Paying a little for the right to miss one payment in a bad year can be cheaper than selling grain at the wrong time to make a payment on time.
For the gap between buying inputs and selling grain, the federal Advance Payments Program is the tool. It advances up to $1 million in total financing against stored grain and livestock. For 2026 the interest-free portion is $250,000 on most commodities and $500,000 for canola, and the Canadian Canola Growers Association is one of the administrators. Check the limit each program year.
Freight, fuel and transport costs that ride on Prairie equipment
On the Prairies, distance is a line item. Grain moves by truck and rail, inputs arrive by truck, and equipment is serviced by a dealer who may be a long drive away. When diesel spikes, every acre costs more to work, so a thirsty engine belongs in the financing decision.
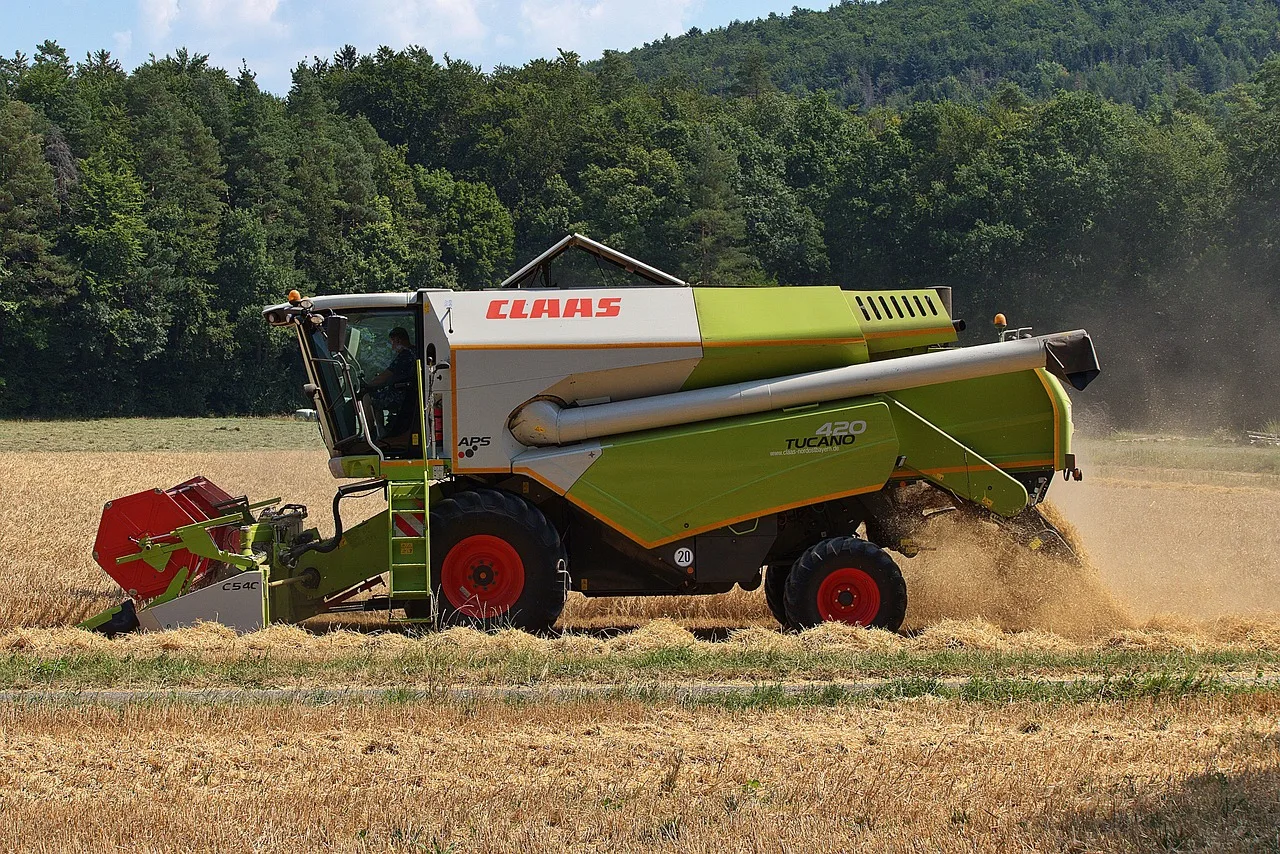
A combine bought in Manitoba and used in Saskatchewan also carries transport, inspection and sometimes tax consequences. Those costs belong in the financing file, not in a separate column.
What Manitoba and Saskatchewan programs add to the stack
The two provinces differ. Manitoba has a provincial farm lender. Saskatchewan has no equivalent that we could confirm, so check what the province offers today.
Manitoba vs Saskatchewan support
Manitoba
- Focus
- Equipment, expansion, seasonal
- Portal
- Business programs page
- Typical gap filled
- Drainage, buildings
- Role
- Fills lender gap
Saskatchewan
- Focus
- Ag, resources, industry
- Portal
- Business gateway
- Typical gap filled
- Younger operators, processing
- Role
- Fills lender gap
In Manitoba, MASC Direct Loans can fund new or used agricultural equipment. MASC lends up to $6.25 million at up to 80 percent financing, with new equipment up to 10 years and previously owned up to 7. Rates can be fixed for the full amortization or renew every one to five years, and payments can be monthly, quarterly or semi-annual.
MASC's Young Farmer Rebate helps farmers aged 18 to 39 who run the farm. It pays up to 2 percent a year on the first part of a loan's principal for the first five years. MASC's pages quote different caps, $400,000 with a $40,000 lifetime limit and $425,000 with $42,500, so confirm the current figures.
In Saskatchewan, farm loans come through FCC, banks, credit unions and CALA guaranteed lending. The province's crop insurance corporation, SCIC, delivers crop insurance, which protects the revenue that repays the loan rather than financing equipment.
Provincial programs rarely replace a lender. They usually fill a gap: a younger operator without a long record, or a piece of equipment a bank will not fully fund. Before you assemble the stack, sort the lenders. The questions to ask equipment financing lenders separate lenders that care most about the machine from those that care about your cash flow. Prairie deals usually need one of each.
Work through the file in order:
- Get the dealer quote in writing, with the machine identified.
- Take it to FCC, your bank and your credit union, and ask each for two structures: a five-year term and a ten-year amortisation.
- Ask the bank whether the file qualifies for a CALA guarantee, and get the cap and fees confirmed in writing.
- Add provincial support only if there is a gap, and ask the lender where it sits in the order of security.
- Set the payment dates against your delivery dates, and sign.